Free Practice Questions for the CIMA Operational F1 Exam (2026 Updated)
At Marks4sure, we are dedicated to providing IT professionals with the most accurate and reliable preparation materials for the CIMA F1 exam. To support your certification journey, we have made a selection of our premium 2026 CIMA Operational practice questions and answers available completely free. You can take this practice test as many times as you need. Every question includes a detailed, expertly verified explanation to ensure you fully grasp the core security concepts before test day.
MNO is a commercial bank. One of MNO ' s clients is FGH, a trading company which sells goods to PQR.
MNO is asked to draw up an instrument between FGH and PQR in respect of goods sold FGH then asks MNO to sell this instrument on its behalf in the discount market MNO does this and pays the proceeds to FGH.
What source of short-term finance is being described here?
The statement of profit or loss for PQ, ST and AB for the year ended 31 December 20X0 are shown below:

1. PQ acquired 80% of its subsidiary, ST, on 1 January 20X0 and 40% of its associate, AB, on 1 September 20X0.
2. Since acquistion PQ has sold goods to ST and AB for $20,000 and $30,000 respectively. At the year end both ST and AB have 50% of these goods remaining in inventory. PQ uses a mark-up of 20% on all of its sales.
3. Since acquisition the goodwill in respect of ST has been impaired by $8,000 and the investment in AB has been impaired by $2,000.
4. PQ uses the fair value method for non-controlling interest at acquisition.
What is the value of the unrealized profit in inventory adjustment required to inventory in PQ ' s consolidated statement of financial position at 31 December 20X0?
ST has an asset that was classified as held for sale at 30 June 20X4. The asset ' s carrying value was $230,000 and its fair value $210,000.
The cost of disposal was estimated to be $15,000.
In accordance with IFRS 5 Non-current Assets Held for Sale and Discontinued Operations, which of the following values should be used for the asset in the statement of financial position as at 30 June 20X4?
Company Y is using some of the money from a share issue to purchase a new office building. The company is also using some of the money to purchase inventories. Which method of financing is this?
In most developed countries employers deduct the tax from employees ' pay each month and then pay the tax to the tax authorities on behalf of the employee on a monthly basis.
Which THREE of the following are advantages of this system to the employee?
While conducting their audit, auditor 0 did not encounter issues which significantly limited the scope of their audit, however they did run into problems in that they disagreed with the management on facts in the
statements.
These disagreements were somewhat material, but they did not affect the auditor ' s overall opinion of the business. Which of the following statements should auditor 0 issue?
MNO is a manufacturer. Which TWO of the following costs will MNO add to the cost of its finished goods inventory in accordance with IAS 2: Inventories?
The International Accounting Standards Board ' s " The Conceptual Framework for Financial Reporting " (known as The Conceptual Framework) states that " faithful representation " is a fundamental qualitative characteristic.
In accordance with the Conceptual Framework which of the following is NOT part of faithful representation?
A specialized product was commissioned by a customer and the agreed price was $38,000. The product was completed at a cost of $34,000.
It was then discovered that new regulations meant that the specialized product now failed health and safety requirements. The specialized product had to be modified to meet the new regulations at a cost of $9,000. The customer agreed to pay an extra $3,000 towards the modifications.
At 31 December 20X5 the specialized product was still in inventory and had not been modified.
Calculate the value of the specialized product that should be included in inventory as at 31 December 20X5.
Give your answer to the nearest whole $000.
For an entity to be exempt from preparing consolidated financial statements it must meet certain criteria specified in IFRS 10 Consolidated Financial Statements.
Which of the following conditions would give exemption from preparing consolidated financial statements?
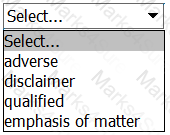
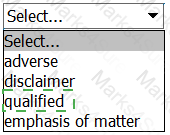
The auditor has identified a material but not pervasive mis-statement whilst undertaking the external audit of an entity ' s financial statements.
This will result in a modified audit report with the opinion being .
CDE has been offering its customers a 50-day credit period, but now wants to improve its cash flow.
CDE is proposing to offer a 2% discount for payment in 20 days. "
Assume a 365-day year and an invoice value of $100
Which of the following is the effective annual interest rate CDE will incur for this action?
AA manufactures computers. These are sold to BB at $100 a computer plus a 5% sales tax. BB subsequently sells the computers to CC for $200 a computer plus a 5% sales tax. C sells the computers to customers at $300 a computer plus a 5% sales tax.
The total tax received by the tax authority is $30.
Which type of tax is described above?
The following information relates to AA.
Extract of Trial Balance at 31 December 20X4;

Notes
(i) Inventory at 31 December 20X4 was valued at cost at $30.
(ii) The loan which was received on 1 July 20X4 is repayable in 20X9.
(iii) Corporate income tax represents an over-provision of tax for the year ended 31 December 20X3. AA reported a loss for tax purposes for the year ended 31 December 20X4 and a tax refund is expected amounting to $20.
(iv) Cost of sales, administration and distribution costs need to be adjusted for the following:
What figures should be entered in the Statement of Profit or Loss for the year ended 31 December 20X4 in relation to Administration and Distribution costs?
The financial statements of JK for the year ended 31 August 20X4 were approved on 10 November 20X4.
Within these financial statements which of the following would have been treated as a non-adjusting event in accordance with IAS 10 Events After the Reporting Period?
The tax rules in a country state that all tax returns must be filed by 31 March each year and that any outstanding tax balance must be paid by 14 April each year. An entity filed its tax return on 10 April 20X2 and paid the outstanding tax on 20 April 20X2.
Which TWO of the following powers is the tax authority likely to have in respect of these actions by the entity?

Statements of financial position for FG, IJ and KL at 31 December 20X5 include the following balances:
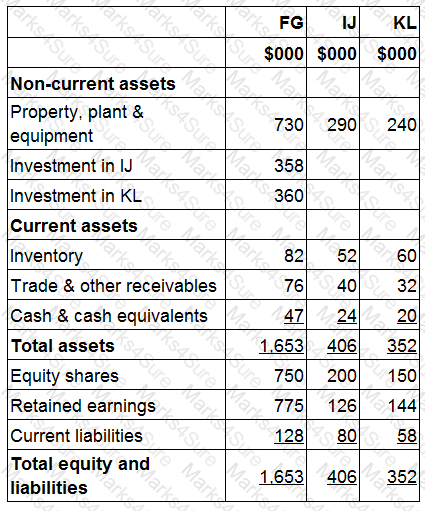
FG acquired 90% of IJ ' s equity shares for $358,000 on 1 July 20X5 when IJ ' s retained earnings were $98,000.
FG acquired 100% of KL ' s equity shares for $360,000 on 1 January 20X5 when KL ' s retained earnings were $155,000.
FG used the proportion of net assets method to value non-controlling interests at acquisition.
KL sold a piece of land to FG for $130,000 on 1 September 20X5. At the date of transfer the land had a carrying value of $50,000.
The management of FG expect KL to make profits in the future and no impairment ot its goodwill was proposed at 31 December 20X5.
Calculate the non-controlling interest balance in FG ' s consolidated statement of financial position at 31 December 20X5.
Give your answer to nearest whole $.
Which of the following is an effect of using equity accounting to include an entity in the consolidated statement of financial position of a group?
Which of the following is NOT a responsibility of the International Accounting Standards Board?
Which THREE of the following are costs that a business might incur as a result of holding insufficient inventory of raw materials?
Statements of financial position for FG, IJ and KL at 31 December 20X5 include the following balances:
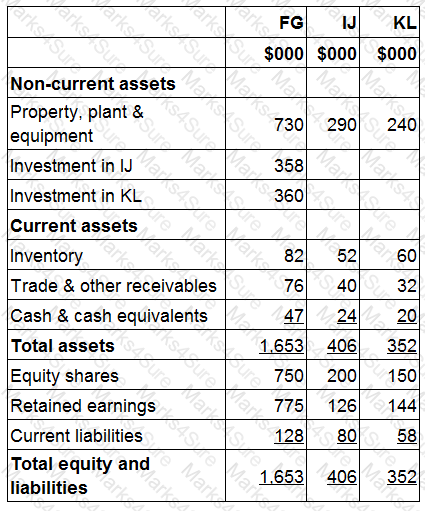
FG acquired 90% of IJ ' s equity shares for $358,000 on 1 July 20X5 when IJ ' s retained earnings were $98,000.
FG acquired 100% of KL ' s equity shares for $360,000 on 1 January 20X5 when KL ' s retained earnings were $155,000.
FG used the proportion of net assets method to value non-controlling interests at acquisition.
KL sold a piece of land to FG for $130,000 on 1 September 20X5. At the date of transfer the land had a carrying value of $50,000.
The management of FG expect KL to make profits in the future and no impairment ot its goodwill was proposed at 31 December 20X5.
Calculate the value of property, plant and equipment to be recognized in FG ' s consolidated statement of financial position at 31 December 20X5.
Give your answer to the nearest whole $.
Statements of financial position for YZ, BC and DE at 31 March 20X2 include the following balances:
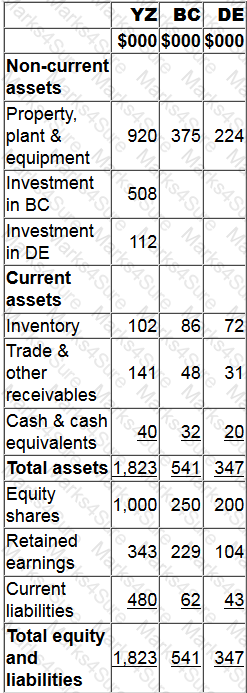
YZ purchased 90% of BC ' s equity shares for $508,000 on 1 January 20X2. On 1 January 20X2 BC ' s retained earnings were $183,000. YZ uses the proportion of net assets method to value non-controlling interest at acquisition.
YZ purchased 30% of DE ' s equity shares on 1 April 20X1 for $112,000. DE ' s retained earnings at 1 April 20X1 were $88,000.
On 1 February 20X2 YZ sold goods to BC for $28,000 at a mark up of 25% on cost. All the goods were still in BC ' s inventory at 31 March 20X2.
Calculate the goodwill arising on the acquisition of BC.
Give your answer to the nearest whole $.
The following information relates to ABC.
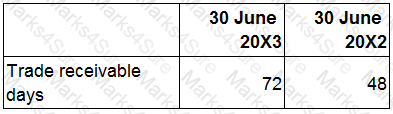
Which of the following would be a reason for the movement in the trade receivable days?
Which of the following is a condition that has to be met for an entity to be exempt the requirement to prepare consolidated financial statements?
PZ has the following working capital ratios:
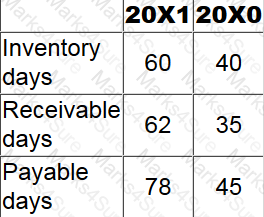
Which of the following could be the reason for the movements?
YZ has $40,000 of plant and machinery which was acquired on 1 June 20X1.Tax depreciation rates on plant and machinery are 25% reducing balance. All plant and machinery was sold for $24,000 on 1 June 20X3.
Calculate the tax balancing allowance or charge on disposal for the year ended 31 May 20X3 and state the effect on the taxable profit.
Which of the following is the responsibility of the International Financial Reporting Standards Interpretations Committee?
In accordance with the Conceptual Framework for Financial Reporting, which of the following describes the historical cost measurement basis for an asset?
Which TWO of the following are implications of employee income tax being paid to the tax authority through a Pay-As-You-Earn scheme?
The following data relates to Company AB.
Statement of Profit or Loss for the year ended 30 June 20X4:
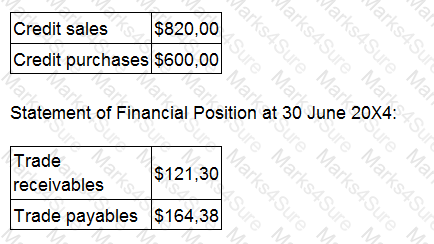
During the year ending 30 June 20X4, which was not a leap year, the average stock holding period was 102 days.
Calculate the working capital cycle in days.
Give your answer to the nearest full day.
DE purchased an asset on 1 January 20X1 for $60,000 with a useful economic life of six years and a residual value of $3,000.
DE uses straight line depreciation for this asset.
On 31 December 20X3 the asset has a value in use of $ $28,000 and a fair value of $26,000.
Which of the following values should be used for the asset in DE ' s statement of financial position as at 31 December 20X3?
In accordance with IAS 16 Property, Plant and Equipment, in which of the following situations would subsequent expenditure on a non-current asset be capitalised?
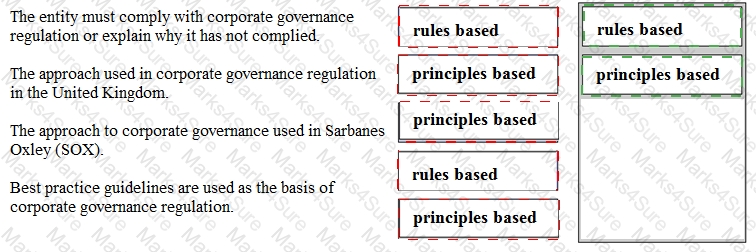
There are two main approaches that a country could adopt in respect of corporate governance regulation - a rules based approach and a principles based approach. Match the following statements with the appropriate approach by placing either rules based or principles based against each of them.

BCD ' s finance cost for the year ended 30 June 20X6 in its statement of profit or loss is $198,000. BCD ' s statement of financial position is as follows:

How much will be included in BCD ' s statement of cash flows for interest paid in the year ended 31 December 20X6?
Give your answer to The nearest $.

In which of the following concepts is profit an increase in the nominal value of capital over a period?
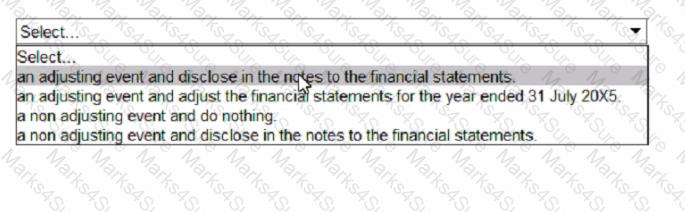
AB has prepared its financial statements for the year ended 31 July 20X5. On 15 September 20X5 a major fraud was uncovered by the external auditors which had taken place during the year to 31 July 20X5 The financial statements have not yet been authorised
In accordance with IAS 10 Events After the Reporting Period, AB should treat the fraud as:
Statements of financial position for FG, IJ and KL at 31 December 20X5 include the following balances:

FG acquired 90% of IJ ' s equity shares for $358,000 on 1 July 20X5 when IJ ' s retained earnings were $98,000.
FG acquired 100% of KL ' s equity shares for $360,000 on 1 January 20X5 when KL ' s retained earnings were $155,000.
FG used the proportion of net assets method to value non-controlling interests at acquisition.
KL sold a piece of land to FG for $130,000 on 1 September 20X5. At the date of transfer the land had a carrying value of $50,000.
The management of FG expect KL to make profits in the future and no impairment ot its goodwill was proposed at 31 December 20X5.
Calculate the amount of retained earnings that will be included in FG ' s consolidated statement of financial position as at 31 December 20X5.
Give your answer to the nearest whole $.
If an entity makes a capital loss in a period, which of the following is the most likely way that will be allowed for relieving that capital loss?
The subsidiary company of Group XY has purchased £150,00 worth of goods its parent company. However the goods purchased have yet to arrive at the subsidiary at the end of the financial year 20X4, meaning there is
a disagreement in the current account balances between the parent and subsidiary.
With Group XY looking to produce its CSOFP for the end of the financial year, which of the following statements are true in relation to accounting for this disagreement? Select ALL that apply.
A building was purchased on 1 January 20X1 for $300,000 and had a useful economic life of 40 years. On 1 January 20X5 the building was revalued by a professional surveyor at $450,000. Directors decided to incorporate the revalued amount into the financial statements.
The accounting entries to record the initial revaluation of the building in the financial statements for the year ended 31 December 20X5 will be to debit building cost $150,000 and then:
Which of the following would be classified as a parent and subsidiary relationship in accordance with IFRS 10 Consolidated Financial Statements?
Which THREE of the following statements are NOT true of the IFRS Foundation trustees?
EFG purchased an asset on 1 January 20X5 for $24,000. On that date its useful life was 5 years and residual value was expected to be nil. EFG calculates depreciation on a pro-rata basis.
The asset is reclassified as held for sale on 1 October 20X8 and is unsold on 31 December 20X8.
It is expected that the asset will be sold for S6;300 and that selling costs will be S500
What is the amount that this asset will be included at in EFG ' s statement of financial position at 31 December 20X8?
Give your answer to the nearest $.
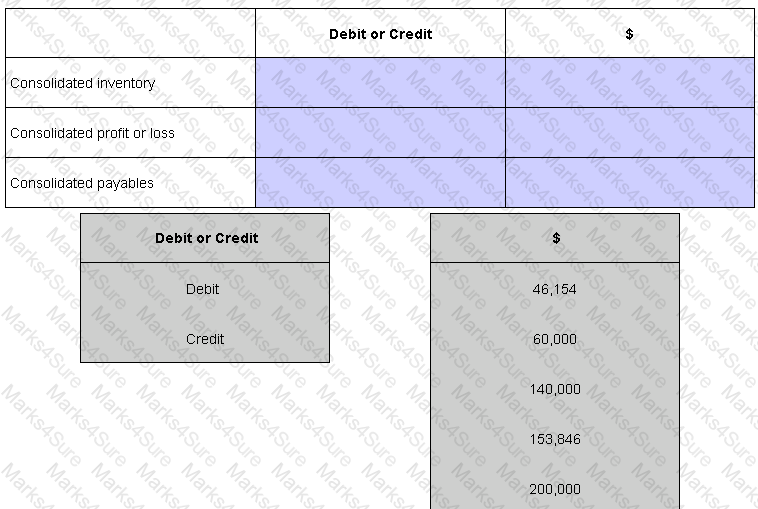
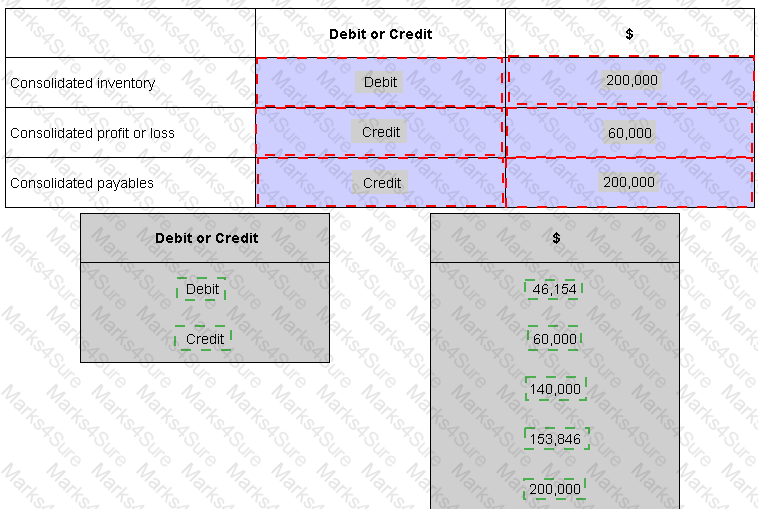
An entity ' s policy is to finance the investment in working capital using short-term financing to fund all of its investment in fluctuating net current assets as well as some of its investment in permanent net current assets.
What is this working capital financing policy known as?
Country A permits the following deductions in an entity ' s annual corporate income tax return in relation to entertaining expenses and gifts;
1 Employee entertaining up to a value of $150 a head
2 Entertaining of overseas customers.
3 Individual gifts not to exceed $10 in value
Which THREE of the following actions would be regarded as tax evasion?
Which TWO of the following are functions of the International Financial Reporting Standards (IFRS) Advisory Council?
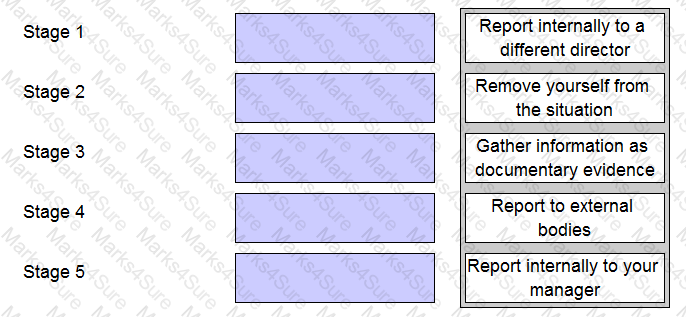
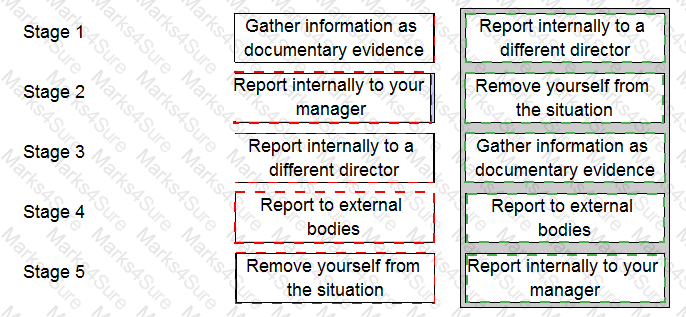
You work in the finance department of an entity. A director has approached you and asked you to falsify sales invoices which would significantly inflate revenue. The CIMA Code of Ethics suggests that you should deal with such an ethical dilemma by following a number of stages.
Place each of the stages identified below into chronological order.
Statements of financial position for YZ, BC and DE at 31 March 20X2 include the following balances:

YZ purchased 90% of BC ' s equity shares for $508,000 on 1 January 20X2. On 1 January 20X2 BC ' s retained earnings were $183,000. YZ uses the proportion of net assets method to value non-controlling interest at acquisition.
YZ purchased 30% of DE ' s equity shares on 1 April 20X1 for $112,000. DE ' s retained earnings at 1 April 20X1 were $88,000.
On 1 February 20X2 YZ sold goods to BC for $28,000 at a mark up of 25% on cost. All the goods were still in BC ' s inventory at 31 March 20X2.
Calculate the value of inventory that will be included in YZ ' s consolidated statement of financial position at 31 March 20X2.
Give your answer to the nearest whole $.
The statement of profit or loss for PQ, ST and AB for the year ended 31 December 20X0 are shown below:
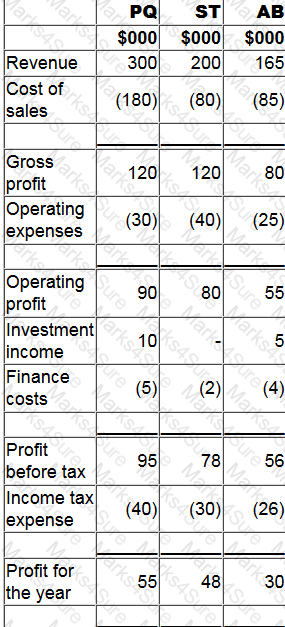
1. PQ acquired 80% of its subsidiary, ST, on 1 January 20X0 and 40% of its associate, AB, on 1 September 20X0.
2. Since acquistion PQ has sold goods to ST and AB for $20,000 and $30,000 respectively. At the year end both ST and AB have 50% of these goods remaining in inventory. PQ uses a mark-up of 20% on all of its sales.
3. Since acquisition the goodwill in respect of ST has been impaired by $8,000 and the investment in AB has been impaired by $2,000.
4. PQ uses the fair value method for non-controlling interest at acquisition.
Calculate the amount that will be shown as the share of profit of associate in PQ ' s consolidated statement of profit or loss for the year ended 31 December 20X0.
Which TWO of the following statements about accounting for associates are true?
JKL prepares its financial statements to 31 December each year. For the year ended 31 December 20X5 inventory was held for 76 days on average.
The directors of JKL decide to reduce the average inventory level to $6.5 million from 1 January 20X6 JKL ' s revenue for 20X6 is $54 million on which a gross profit margin of 20% is earned.
Assuming that the average receivables and payables days remain constant what will be the effect of the expected reduction in inventory on JKL ' s working capital cycle for the year ended 31 December 20X6?
AB has been asked to analyze the receivables days of an entity with a view to improving the working capital cycle.
The following results have been produced for receivable days:
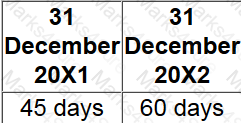
Which of the following is NOT an explanation of why the days have increased?
The following information relates to AA.
Extract of Trial Balance at 31 December 20X4;
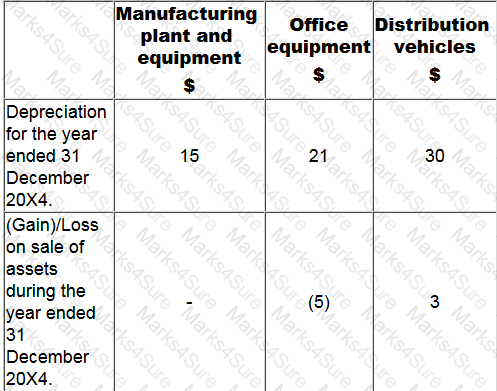
Notes
(i) Inventory at 31 December 20X4 was valued at cost at $30.
(ii) The loan which was received on 1 July 20X4 is repayable in 20X9.
(iii) Corporate income tax represents an over-provision of tax for the year ended 31 December 20X3. AA reported a loss for tax purposes for the year ended 31 December 20X4 and a tax refund is expected amounting to $20.
(iv) Cost of sales, administration and distribution costs need to be adjusted for the following:
What figures should be entered on the face of the Statement of profit or Loss for the year ended 31 December 20X4 in relation to Interest and Corporate income tax?
XY purchased a building on 1 April 20X1 for $300,000 with a useful economic life of 30 years. On 1 April 20X7 the building was revalued at $525,000.
What will the new depreciation charge be following the revaluation?
Give your answer as a whole number.
Which THREE of the following are included within an entity ' s statement of profit or loss?
Which of the following would NOT be classified as part of non-current assets in a statement of financial position?
AB sells to ST, a group entity, 10,000 units at $2.50 each. The market value was $6 each.
The effect on AB of the transfer pricing legislation on this transaction would be to: .
DEF is considering introducing a Pay-As-You-Earn (PAYE) system but unsure of the advantages of using it.
Which of the following statements are advantages from the employees perspective of an entity using a PAYE system for collecting taxes from employees.
Select ALL that apply.
For an incorporated business, the taxation of trading income is a form of direct taxation which is based on:
OP holds an investment property purchased on 1 January 20X3 for $700,000 with a useful economic life of 25 years.
At 31 December 20X5 the fair value of the investment property was $750,000 with a revised useful economic life of 25 years from that date.
OP has been carrying the investment property using the cost model until 31 December 20X5.
The directors wish to change their valuation method to fair value in accordance with IAS 40 Investment Property.
Which of the following is the correct treatment of the revaluation gain and the value of the property in the statement of financial position at 31 December 20X5?
STU has a non-current asset which originally cost $250,000, has an expected life of 8 years and an estimated residual value of $25,000. The asset is depreciated at 25% a year on a reducing balance basis On 1 July 20X5 the accumulated depreciation for this asset is $109,375
What is the depreciation charge for the year ending 30 June 20X6?
Give your answer to the nearest whole number.
ABC has the following working capital ratios at 31 December 20X2:
 During the year ended 31 December 20X4 credit purchases were $1,700,000 and at 31 December 20X4 the outstanding trade payables balance was $340,000
Calculate the working capital cycle for ABC.
Give your answer to the nearest whole number of days and assume there are 365 days in a year.

PDF + Testing Engine
Testing Engine
PDF (Q&A)